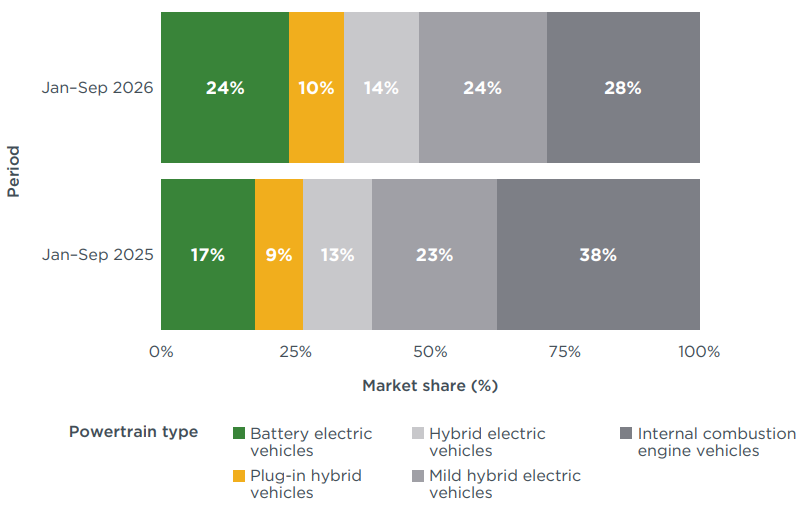
In September 2026, 31% of new vehicles in Europe were battery electric. This brings the average share for January–September 2026 to 24%, a 7-percentage point or 45% increase over the same period in 2025.[1]Meanwhile, the market share of plug-in hybrid cars increased 1 percentage point, reaching a 10% share.
Registrations of conventional combustion engine cars fell by 10 percentage points to a 28% market share in January–September 2026, while mild hybrids and full hybrids increased their shares to 24% and 14%, respectively, an increase of 1 percentage point for each vehicle type.
Germany and France, Europe’s largest car markets, registered battery electric market shares of 28% and 31%, respectively, representing increases of 9 and 13 percentage points compared with January–September 2025.
Italy, Europe’s third-largest market, recorded growth, with a battery electric share of 8%, 3 percentage points higher than in January–September 2025. In Poland, Europe’s fifth-largest market, the market share fell by 1 percentage point, to 5%.
Among the seven largest automakers in Europe, BMW Group registered the highest share of battery electric cars in January–September 2026 with 31%, while the Mercedes-Benz Group recorded the largest increase, up 10 percentage points from the same period in 2025. The Volkswagen Group, by far the largest manufacturer with a 28% market share, increased both its battery electric and plug-in hybrid shares by 2 percentage points. Toyota nearly tripled its battery electric share from 4% to 11%.
More than 1.20 million public chargers had been installed in Europe by the end of September 2026, up 13% from a year earlier. Belgium recorded the strongest growth, with a 34% increase in direct current (DC) chargers and a 29% increase in alternating current (AC) chargers between September 2026 and September 2025.
Spanish market
Spain, Europe’s fourth-largest market, also grew. The market share of battery electric vehicles (BEVs) reached 11% between January and September 2026, three percentage points higher than in the same period in 2025. In September 2026, the monthly BEV share reached 18%, with 17,644 units (+71% compared with September 2025). So far this year, 103,016 BEVs have been registered, 39% more.
Plug-in hybrid vehicles (PHEVs) recorded 120,305 registrations between January and September 2026, 36% more than the previous year, and reached a 13% share (compared with 10% in 2025). In September, their monthly share was 16%, with 14.910 units (+40%). Together, electric and plug-in hybrid vehicles already account for 24% of new registrations in Spain so far this year, six points more than in 2025. In September, they reached 34%.
Conventional hybrids (HEVs) grew more than any other type: 204.202 units (+35%) and a 22% share, five points more than in 2025. This is one of the highest shares among the ten largest European markets, together with Poland (24%) and France (21%). In September, HEVs increased by 27% and reached 22% of the market. Mild hybrids (MHEVs) maintained a 24% share, with 222.757 registrations (+9%).
In total, the Spanish market recorded 932,886 passenger cars between January and September 2026, 7% more than in the same period in 2025. In September alone, 95,942 passenger cars were registered (+11%).
CO2 emissions from the sector
For the period from January 2025 to September 2026, manufacturer pools were on average meeting the carbon dioxide (CO2) emissions target for 2025–2027.
¹ Geographical scope: To the extent permitted by the available data, the definition of Europe used in the ICCT Market Monitor reports is aligned with EU regulations. European CO₂ standards for passenger cars and vans apply to the countries of the European Economic Area (EEA), with the exception of Liechtenstein. This includes the 27 Member States of the European Union, as well as Iceland and Norway.
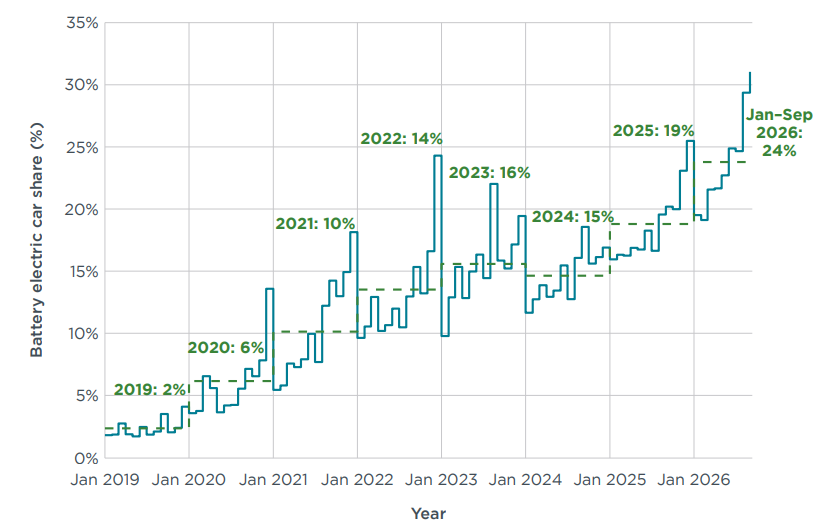
In September 2026, new battery electric vehicle (BEV) registrations made up 31% of all newly registered vehicles. This brought the average share of BEVs among total new registrations in Europe to 24% in January–September 2026, surpassing the 2025 average by 5 percentage points and marking a 7-percentage-point or 45% increase compared with the same period in 2025 (see Figure 1). The market share of plug-in hybrid vehicles (PHEVs) averaged 10% for January–September 2026.
Figure 1
Share of battery electric vehicles among new passenger car registrations in Europe
Compared with the same period in 2025, full hybrid electric vehicles (HEVs) and mild hybrid electric vehicles (MHEVs) increased in market share by 1 percentage point each, respectively, reaching shares of 14% and 24% in January–September 2026. Meanwhile, conventional internal combustion engine vehicles (ICEVs) comprised 28% of new registrations in January–September 2026. This was 10 percentage points lower than the market share during the same period in 2025 (see Figure 2).
Figure 2
Europe’s new car market share by powertrain type, January–September 2026 versus January–September 2025
Compared with January–September 2025, total new registrations in January–September 2026 among the 10 largest European markets generally increased, with Austria (+12%) and Poland (+10%) recording the largest increases. Total new registrations decreased in the Netherlands (−2%) and Belgium (−1%; see Table A5 in the Appendix).
Looking at new BEV registrations in January–September 2026, Germany and France—Europe’s largest car markets—had BEV market shares of 28% and 31%, respectively. These represent increases of 9 and 13 percentage points, respectively, compared with the same period in 2025.
Italy and Spain, the third- and fourth-largest markets, had both increases of 3 percentage points in January–September 2026, reaching BEV shares of 8% and 11%, respectively.
Nordic countries led Europe in BEV registration shares, with Norway and Denmark reaching shares of 98% and 82%, respectively, in January–September 2026, followed by Finland (51%), Iceland (50%) and Sweden (44%). The Netherlands (42%), Belgium (39%), France (31%), Luxembourg (31%), Germany (28%), Portugal (26%), Austria (26%), and Ireland (26%) all had BEV shares of 25% or more (Figure 3). In January–September 2026, Denmark recorded the highest growth of all countries in BEV market share (+16 percentage points) compared with the same period in 2025. Among the ten largest markets, France stood out with a rise of 13 percentage points. Poland was the only market where the battery electric share declined (-1 percentage point).
Figure 3
Europe’s new car market share by country and powertrain type, January–September 2026
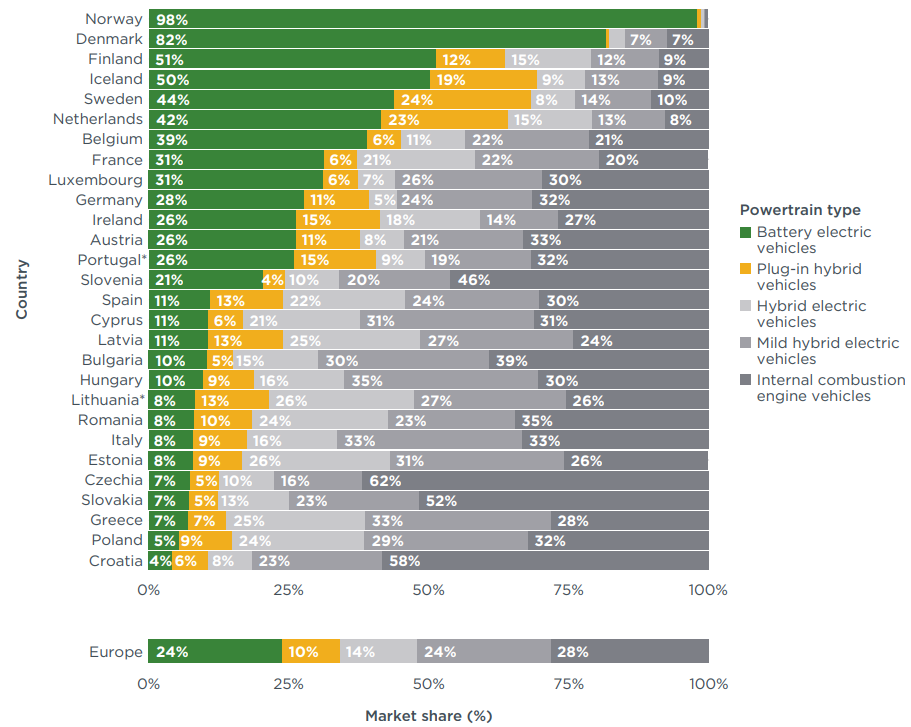
Looking at other powertrains in the 10 largest European markets, PHEV shares were the highest in Sweden (24%) and the Netherlands (23%) in January–September 2026. Poland (24%), Spain (22%) and France (21%) had the highest HEV shares, while MHEV shares were the highest in Italy, at 33%, followed by Poland with 29%.
Under EU regulations, carmakers are required to reduce CO2 emissions from new cars incrementally through 2035. The current target value applies for each year from 2025 to 2029. However, compliance with the targets will first be assessed at the end of 2027 and will consider average CO2 emissions for new car fleets over the 2025–2027 period. Automakers are permitted to combine their emissions performance across these 3 years through pooling arrangements (manufacturing pools) and may use compliance credits earned by selling zero- and low-emission vehicles (ZLEVs) as well as by deploying eco-innovations (i.e., technologies that deliver real-world CO2 savings beyond what is measured over the standardized test cycle during type approval). Increasing the share of battery electric cars is the leading strategy used by manufacturers to achieve these reductions and avoid penalties.
Figure 4
Average distance to 2025–2027 CO2 targets for manufacturer pools and individual manufacturers
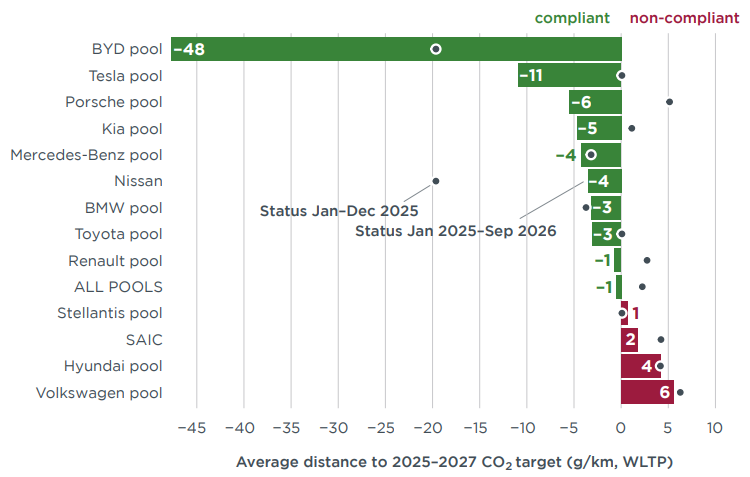
Note: Emission values include compliance credits. All CO2 values are estimates according to the Worldwide harmonized Light vehicles Test Procedure (WLTP). Only individual manufacturers with at least 1% market share in 2025 are shown. See the section on definitions, data sources, methodology, and assumptions for more information.
The Porsche and Tesla pools had the largest BEV registration shares in September 2026, at 79% and 58%, respectively. The Kia (44%), Mercedes-Benz (43%), BYD (37%), and BMW (36%) pools also had shares above the European average of 31%. Nissan (17%) and the Toyota pool (13%) had the lowest BEV shares in September (see Table A1 in the Appendix).
Looking at individual car brands with market shares of 1% or greater in 2025, Tesla and BYD had the greatest over-compliance at 92 g CO2/km and 73 g CO2/km, respectively, below their projected brand-level average targets for 2025–2027 at the end of September 2026, followed by Volvo (28 g CO2/km below), Mini (18 g CO2/km below), and Cupra (16 g CO2/km below). Nissan (24 g CO2/km above), SEAT (23 g CO2/km above), Mazda (21 g CO2/km above), Dacia (14 g CO2/km above), Mercedes-Benz and Audi (each 13 g CO2/km above) had the largest target gaps (see Table A4 in the Appendix).
Among the largest carmakers, the BMW Group had the highest BEV share in January–September 2026 at 31%, up 5 percentage points compared with January–September 2025, while the Mercedes-Benz Group recorded the greatest growth (+10 percentage points). The Hyundai and Renault groups recorded increases of 9 and 8 percentage points in their BEV shares, respectively, while the Toyota Group nearly tripled its share from 4% to 11% (Table 1). The Volkswagen Group, with a 26% total market share in January–September 2026, increased its BEV and PHEV shares by 2 percentage points each relative to the same period in 2025, while the other carmakers recorded either declines or no changes in their PHEV shares.
Table 1
Share of battery electric and plug-in hybrid cars for the top seven manufacturer groups, January–September 2026.
| Manufacturer group | Battery electric car share | Plug-in hybrid car share | Market share Jan–Sept 2026 | ||
| Jan–Sept 2026 | Change vs. Jan–Sept 2025 | Jan–Sept 2026 | Change vs. Jan–Sept 2025 | ||
| BMW Group | 31% | +5 pp | 13% | –3 pp | 7% |
| Hyundai Group | 28% | +9 pp | 4% | –2 pp | 7% |
| Mercedes-Benz Group | 28% | +10 pp | 16% | –4 pp | 5% |
| Volkswagen Group | 21% | +2 pp | 12% | +2 pp | 26% |
| Renault Group | 20% | +8 pp | 1% | <1 pp | 10% |
| Stellantis | 16% | +4 pp | 2% | <1 pp | 15% |
| Toyota Group | 11% | +7 pp | 7% | –2 pp | 7% |
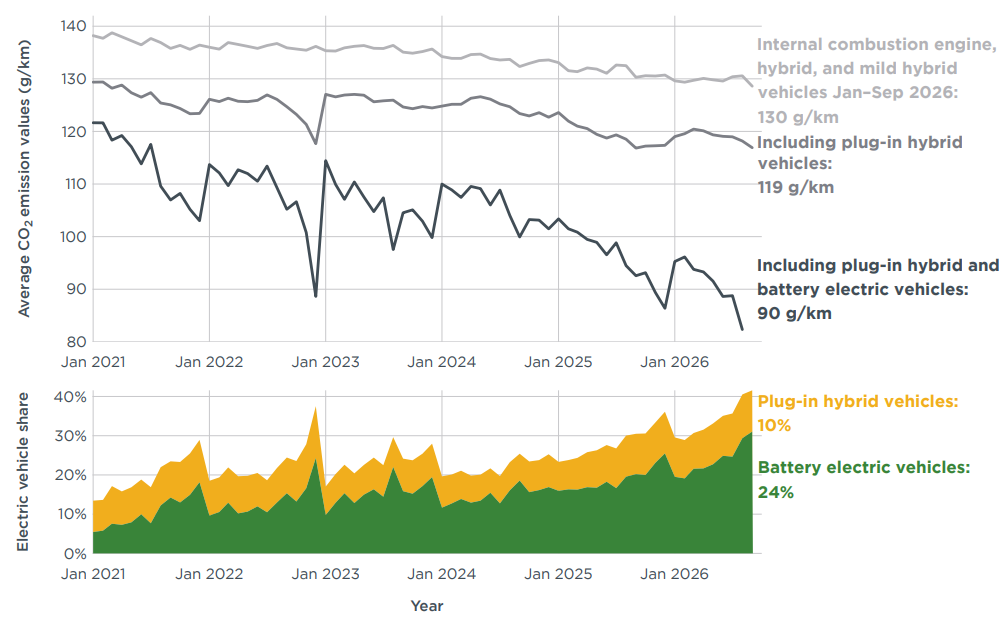
Of all powertrain types, battery electric cars have the largest potential to reduce fleet average CO2 emissions. When looking at new registrations of ICEVs (including HEVs and MHEVs) alone, CO2 emissions averaged 130 g CO2/km in January–September 2026. Including PHEVs reduced the average to 119 g CO2/km, while the increasing market share of BEVs reduced average CO2 emissions by an additional 29 g CO2/km in January–September 2026 (see Figure 5).
Figure 5
Average CO2 emissions of newly registered internal combustion engine vehicles and fleet-average reductions associated with including electrified powertrains
² Marie Rajon Bernard et al., The EV Transition Check: Measuring Progress towards Zero-Emission for Passenger Cars in the European Union (International Council on Clean Transportation, 2025), https://theicct.org/publication/ev-transition-check-sep25/.
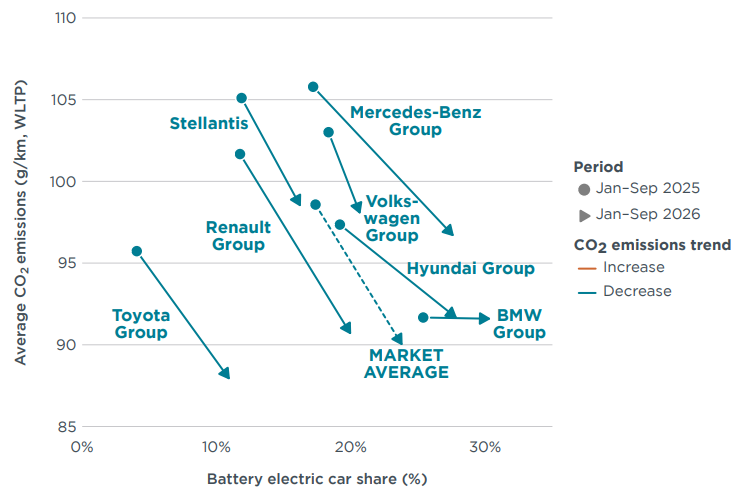
Looking at the relationship between electric car shares and average CO2 emissions in January–September 2026, the Mercedes-Benz Group stood out among the top manufacturers in Europe with some of the highest average emissions despite also having one of the highest shares of BEVs. This was largely driven by the high average CO2 emissions of the Group’s non-electrified powertrains, which stood at roughly 159 g CO2/km in January–September 2026, the highest level among Europe’s largest carmaker groups. In contrast, the Toyota Group, which has focused on hybrid powertrains, recorded average CO2 emissions below its 2026 target and the lowest among the top manufacturers in January–September 2026, despite having the lowest electric vehicle share.
Among Europe’s top manufacturers, BMW Group was the only manufacturing group whose emissions barely decreased in January–September 2026 compared with the previous year. This was partly due to a change in recorded PHEV emissions to more realistic levels resulting from the European Commission’s correction of the electric driving share assumed for type approval at the beginning of the year. However, it also mirrors a trend observed in previous CO2 target cycles: without interim annual targets, manufacturers often scale back CO2 reduction efforts once meeting their defined emissions target instead of using the momentum to reach the next target on a continuous reduction pathway (Figure 6).
Figure 6
Fleet-average CO2 emissions compared with battery electric vehicle share by manufacturer group, January–September 2026 versus January–September 2025
³ Sonsoles Díaz et al., CO₂ Emissions from New Passenger Cars in Europe: Car Manufacturers’ Performance in 2024 (International Council on Clean Transportation, 2025), https://theicct.org/publication/co2-emissions-from-new-passenger-cars-in-europe-car-manufacturers-performance-in-2024-dec25/.
The deployment of public charging infrastructure is expanding steadily in Europe. Over 1.20 million public charging points had been installed in Europe by the end of the third quarter (Q3) of 2026, up from around 1.07 million at the end of Q3 2025. For AC charging, this represents an 11% increase since the end of Q3 2025, while DC charging points showed even greater growth, increasing by 22% since the end of Q3 2025. By the end of September 2026, approximately 78% of Europe’s public charging points supplied AC, while the remaining 22% supplied DC.
Among the 10 markets with the highest number of installed chargers, Belgium recorded the largest growth in DC chargers by the end of Q3 2026 (+34%) compared with the end of Q3 2025, followed by Italy (+31%) and Denmark (+27%). At +26%, Belgium also saw the largest growth in AC chargers (Table 2).
Table 2
Number of publicly accessible charging points by country and power output
| Country | End of Q3/2026 | vs. end of Q3/2025 | ||
| AC | DC | AC | DC | |
| Netherlands | 234,375 | 8,712 | 20% | 24% |
| Germany | 163,651 | 61,642 | 12% | 25% |
| France | 124,598 | 46,414 | 0% | 18% |
| Belgium | 110,461 | 9,298 | 26% | 34% |
| Italy | 61,341 | 20,899 | 7% | 31% |
| Sweden | 52,643 | 13,000 | 8% | 19% |
| Denmark | 45,172 | 10,329 | 12% | 27% |
| Spain | 37,569 | 16,769 | 2% | 19% |
| Austria | 22,195 | 9,490 | -24% | -2% |
| Norway | 16,150 | 15,087 | -5% | 10% |
| Other | 76,526 | 50,858 | 7% | 29% |
| Total | 944,681 | 262,498 | 11% | 22% |
Note: See the section on definitions, data sources, methodology, and assumptions for details.
At the end of Q3 2026, there were on average roughly 10.1 22 kW-equivalent publicly accessible charging points installed per thousand passenger cars and vans on the road in Europe, up from 8.0 at the end of Q3 2025 (Figure 7). With about 47 22 kW-equivalent publicly accessible charging points per thousand passenger cars and vans, Denmark led Europe in charging infrastructure, followed by Norway (43), Sweden (33), and Belgium (26). Italy (4) and Spain (4) fell below the European average for publicly accessible charging points.
Figure 8
22 kW-equivalent publicly accessible charging points installed per thousand passenger cars and vans, by power output and country, by the end of Q3 2026
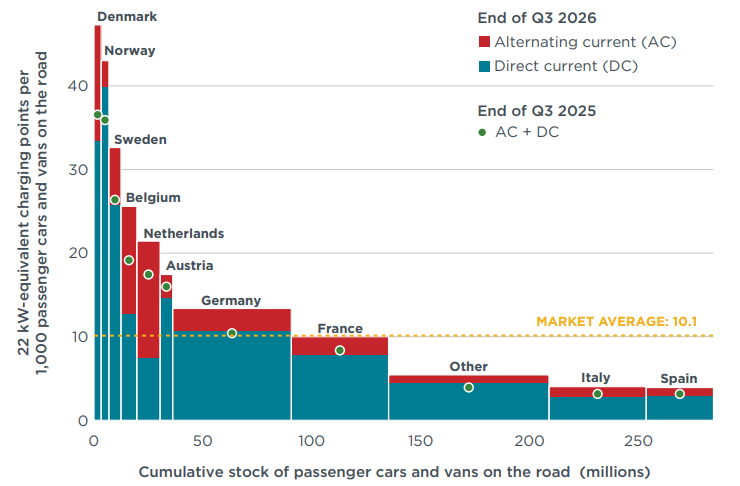
Note: The width of the bars corresponds to passenger car and van stock size estimates as of the end of 2025. 22 kW-equivalent is used to account for different power outputs while allowing for comparison among countries and over time independent of electric vehicle uptake.
The think tanks Agora Verkehrswende (Germany), alinnea (Spain), ECCO Climate (Italy), the International Council on Clean Transportation (ICCT), the Mobility in Transition Institute (IDDRI-IMT, France), and the Polish Association for New Mobility (PSNM, Poland) publish monthly data on the average specific emissions of newly registered vehicle fleets in the European Economic Area, both overall and by country.
These data make it possible to track manufacturers’ compliance gap with respect to the CO₂ reduction targets (Regulation 2019/631) set for the 2025–2027 period, as well as the reduction of CO₂ emissions from new vehicles through 2035.
alinnea provides the report data with a particular focus on Spain, the fourth-largest automotive market in Europe.