As the transition to zero-emission electrified mobility accelerates, monitoring developments in the automotive market becomes an important benchmark for assessing how manufacturers are adapting their strategies to meet increasingly stringent emissions reduction targets.
To provide reliable and up-to-date data to the public debate, the think tanks Agora Verkehrswende (Germany), alinnea (Spain), ECCO Climate (Italy), the International Council on Clean Transportation (ICCT), the Institute for Mobility in Transition (IDDRI-IMT, France), and the Polish New Mobility Association (PSNM) publish monthly data on the average specific emissions of newly registered vehicle fleets across the European Economic Area, both at the aggregate and country level.
These data make it possible to track manufacturers’ compliance gap with the CO₂ reduction targets set for the 2025-2027 period under Regulation (EU) 2019/631, as well as progress towards the reduction of CO₂ emissions from new vehicles through to 2035.
alinnea provides the report’s findings with a particular focus on Spain, Europe’s fourth-largest automotive market.
The monitoring also includes detailed registration data by powertrain type, covering battery electric vehicles (BEVs), plug-in hybrid electric vehicles (PHEVs), full hybrids (HEVs), and mild hybrids (MHEVs). In addition, it provides a quarterly update on developments in charging infrastructure, the production, purchase and registration of vans, and the uptake of corporate electric vehicles.
Through these regular updates, our aim is to provide a valuable resource for automotive manufacturers, analysts, public authorities, trade unions, and environmental organisations. In short, for all stakeholders involved in the transition to zero-emission mobility.
The European Car Market Monitor will be published each month on alinnea’s website and will be distributed to the media and to members of the alinnea Community involved in electric mobility.
In January–July 2026, Europe’s battery electric car registrations recorded a 22% market share, up 5 percentage points from the same period in 2025.1 Meanwhile, the market share of plug-in hybrid cars increased 1 percentage point, reaching a 10% share.
Germany and France, Europe’s largest car markets, registered battery electric market shares of 26% and 29%, respectively, representing increases of 8 and 11 percentage points compared with January–July 2025.
Italy and Spain, the third- and fourth-largest European markets, also saw growth, with battery electric shares reaching 8% and 10%, respectively, up 3 and 2 percentage points from January–July 2025 (1). In Poland, Europe’s fifth-largest market, the market share remained unchanged at 5%.
From January 2025 to July 2026, adjusted carbon dioxide (CO2) emissions among manufacturer pools stood at approximately 94 g/km on average, 1 gram away from the average EU manufacturer target for 2025–2027 of 93 g/km.
1 Geographic scope: To the greatest extent permitted by data availability, the definition of Europe used in the ICCT’s Market Monitor reports aligns with EU regulations. The European CO2 standards for cars and vans applies to the countries of the European Economic Area (EEA), excluding Liechtenstein. This includes the 27 Member States of the European Union plus Iceland and Norway.
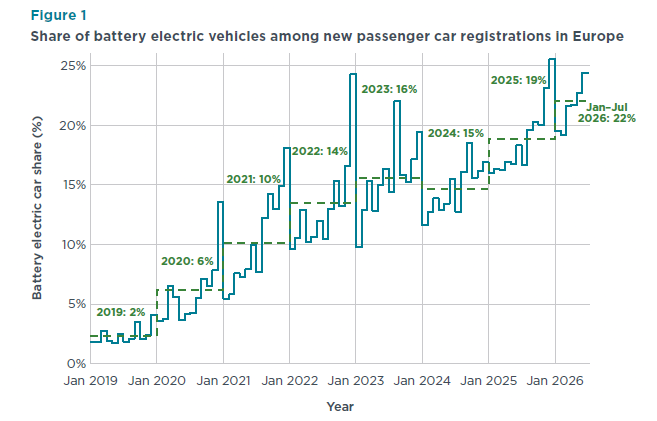
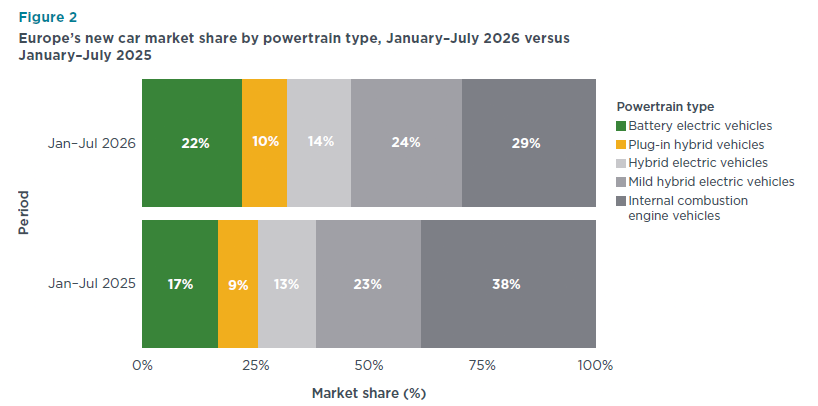
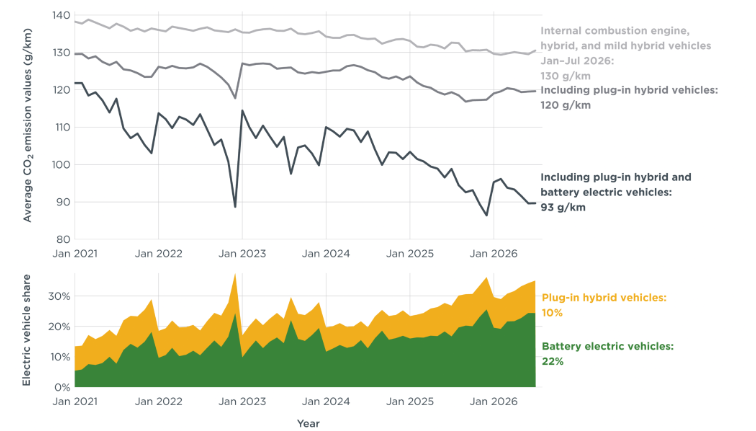
In July 2026, new battery electric vehicle (BEV) registrations reached a 24% share of all newly registered vehicles. This brought the average share of BEVs among total new registrations in Europe to 22% in January–July 2026, surpassing the 2025 average by 3 percentage points and marking a 5-percentage-point increase compared with the same
period in 2025 (see Figure 1). Growth in the market share of plug-in hybrid vehicles (PHEVs) was more modest. In January–July 2026, PHEVs accounted for an average of
10% of new car registrations in Europe, up 1 percentage point from January–July 2025.
Compared with the same period in 2025, full hybrid electric vehicles (HEVs) and mild hybrid electric vehicles (MHEVs) increased in market share by 1 percentage point each, respectively, reaching shares of 14% and 24% in January–July 2026. Meanwhile, conventional internal combustion engine vehicles (ICEVs) comprised 29% of new registrations in January–July 2026. This was 9 percentage points lower than the market share during the same period in 2025 (see Figure 2).
Compared with January–July 2025, total new registrations among the 10 largest European markets increased the most in Poland (+12%) and France (+9%) in January– July 2026, while the largest decreases were recorded in Belgium (−7%), Czechia (−3%) and the Netherlands (−2%; see Table A5 in the Appendix).
Looking at new BEV registrations in January–July 2026, Germany and France—Europe’s largest car markets—had BEV market shares of 26% and 29%, respectively. These represent increases of 8 and 11 percentage points, respectively, compared with the same period in 2025.
Italy and Spain, the third- and fourth-largest markets, had increases of 3 and 2 percentage points in January–July 2026, reaching BEV shares of 8% and 10%, respectively.
Nordic countries led Europe in BEV registration shares, with Norway and Denmark reaching shares of 98% and 80%, respectively, in January–July 2026, followed by Finland (49%) and Iceland (44%). Sweden (42%)2, the Netherlands (38%), Belgium (37%), Luxembourg (30%), France (29%), Germany (26%), Ireland (25%), and Austria (25%) all had BEV shares of 25% or more (Figure 3). In January–July 2026, Denmark recorded the greatest increase in BEV market share (+16 percentage points) compared with the same period in 2025.
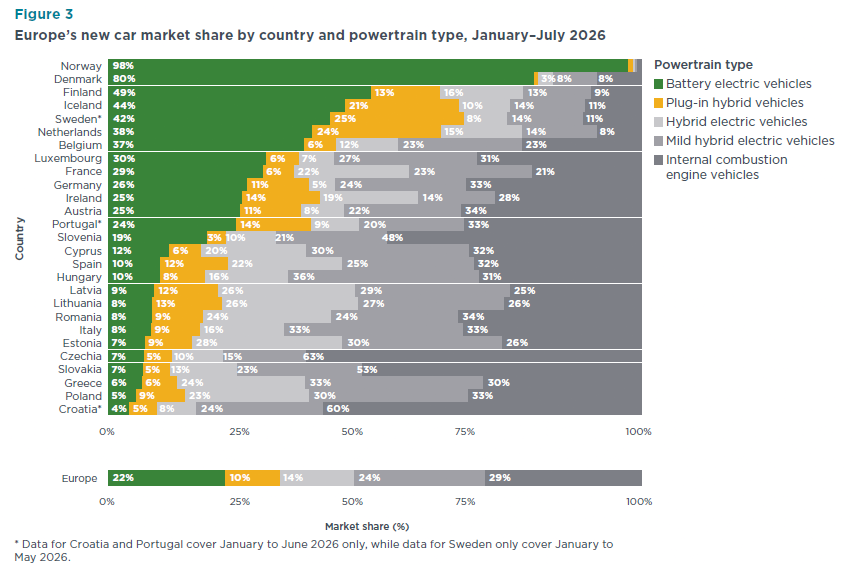
Looking at other powertrains in the 10 largest European markets, PHEV shares were the highest in Sweden (25%) and the Netherlands (24%) in January–July 2026.3 Poland (23%), France (22%), and Spain (22%) had the highest HEV shares, while MHEV shares were the highest in Italy, at 33%, followed by Poland with 30%.
Under EU regulation, carmakers are required to reduce CO2 emissions from new cars incrementally through 2035. The current target value applies for each year from 2025 to 2029. However, compliance with the targets will first be assessed at the end of 2027 and will consider average CO2 emissions for new car fleets over the 2025–2027 period. Automakers are permitted to combine their emissions performance across these 3 years through pooling arrangements (manufacturing pools) and may use compliance credits earned by selling zero- and low-emission vehicles (ZLEVs) as well as by deploying eco-innovations (i.e., technologies that deliver real-world CO2 savings beyond what is measured over the standardized test cycle during type approval). Increasing the share of battery electric cars is the leading strategy used by manufacturers to achieve these reductions and avoid penalties.
In January–July 2026, manufacturer CO2 emissions averaged 93 g CO2/km (excluding compliance credits). After accounting for compliance credits, manufacturers were, on average, in compliance with the 2026 target (see Table A2 of the Appendix). For the full reporting period from January 2025 to July 2026, adjusted emissions stood at around 94 g CO2/km. When including compliance credits, manufacturing pools thus remained 1 g CO2/km short of the average target of 93 g CO2/km for the 2025–2027 period (see Table A3 in the Appendix).
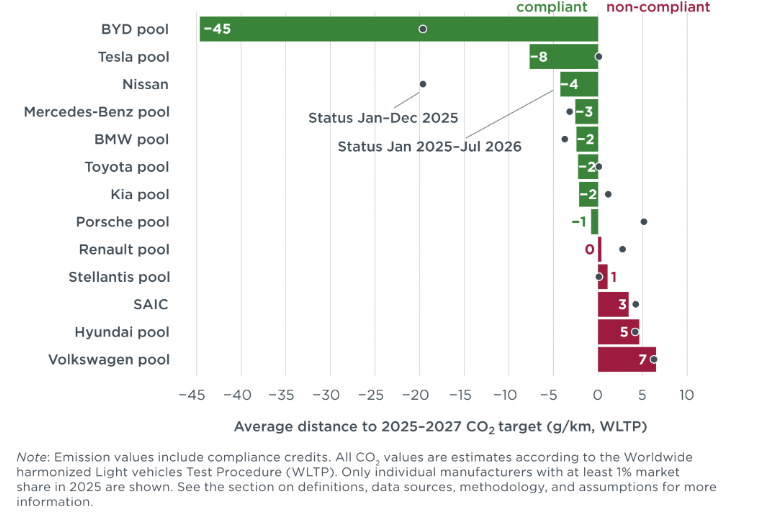
For the full January 2025–July 2026 reporting period, the BYD pool (45 g CO2/km below), the Tesla pool (8 g CO2/km below), Nissan (4 g CO2/km below), the Mercedes- Benz pool (3 g CO2/km below), the Toyota, BMW, and Kia pools (each 2 g CO2/km below), the newly formed Porsche pool (1 g CO2/km below), and the Renault pool (at target) were all on track to meet their 2025–2027 targets. Together, these pools accounted for approximately 48% of new registrations in January–July 2026. At the other end of the spectrum, the Volkswagen pool, which accounted for the largest market share (26%), remained the furthest from its target, exceeding it by 7 g CO2/km. Its emissions did not change significantly with the departure of Porsche from the pool (see Figure 4): compared with a scenario in which Porsche remained in the pool in 2026, the pool’s CO2 emissions in January–July 2026 were less than 1 g/km lower.
Figure 4 Average distance to 2025-2027 Co2 targets for manufacturer pools and individual manufaturers
The Porsche and BYD pools had the largest BEV registration shares in July 2026, at 70% and 37%, respectively. The Kia (35%), Mercedes-Benz (34%), BMW (34%), and Tesla (26%) pools also had shares above the European average of 24%. The Stellantis pool (18%) and Toyota pool (11%) had the lowest BEV shares in July (see Table A1 in the Appendix).
Looking at individual car brands with market shares of 1% or greater, Tesla and BYD had the greatest over-compliance at 92 g CO2/km and 74 g CO2/km, respectively, below
their projected brand-level average targets for 2025–2027 at the end of July 2026, followed by Volvo (27 g CO2/km below), Mini (17 g CO2/km below), and Cupra (15 g CO2/km below). Nissan (26 g CO2/km above), SEAT (23 g CO2/km above), Mazda (22 g CO2/km above), Mercedes-Benz (15 g CO2/km above), Audi (15 g CO2/km above), and Dacia (14 g CO2/km above) had the largest target gaps (see Table A4 in the Appendix).
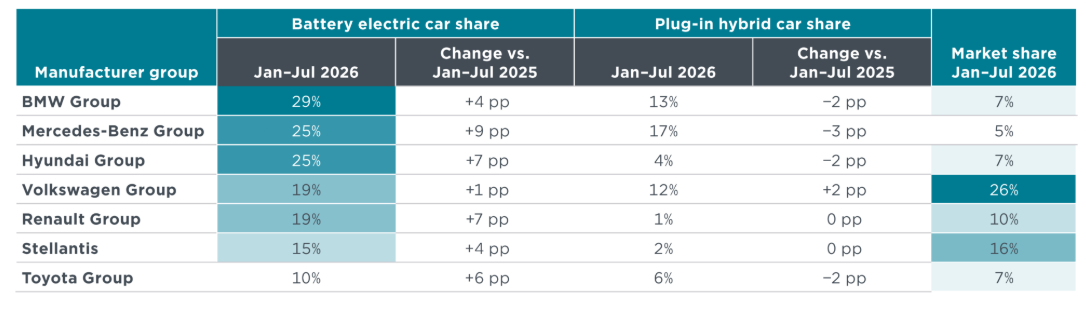
Among the largest carmakers, the BMW Group had the greatest BEV share in January–July 2026 at 29%. The Mercedes-Benz Group increased its BEV share by 9 percentage points compared with January–July 2025. The Hyundai and Renault groups recorded increases of 7 percentage points in each of their BEV shares, while the Toyota Group more than doubled its share from 4% to 10% (Table 1). Meanwhile, with a 26% total market share in January–July 2026, the Volkswagen Group increased its PHEV share by 2 percentage points relative to the same period in 2025, while the other carmakers recorded either marginal or no changes in their PHEV shares.
Table 1 Share of battery electric and plug-in hybrid cars for the top seven manufacturer groups, January – July 2026
Of all powertrain types, battery electric cars have the largest potential to reduce total CO2 emissions.4 When looking at new registrations of ICEVs (including HEVs and MHEVs) alone, CO2 emissions averaged 130 g CO2/km in January–July 2026. Including PHEVs reduced the average to 120 g CO2/km, while the increasing market share of BEVs reduced average CO2 emissions by an additional 27 g CO2/km in January–July 2026 (see Figure 5).
Figure 5 Average CO2 emissions of newly registered internal combustion engine vehícles
and fleet-average reductions associated with including electrified powertrains
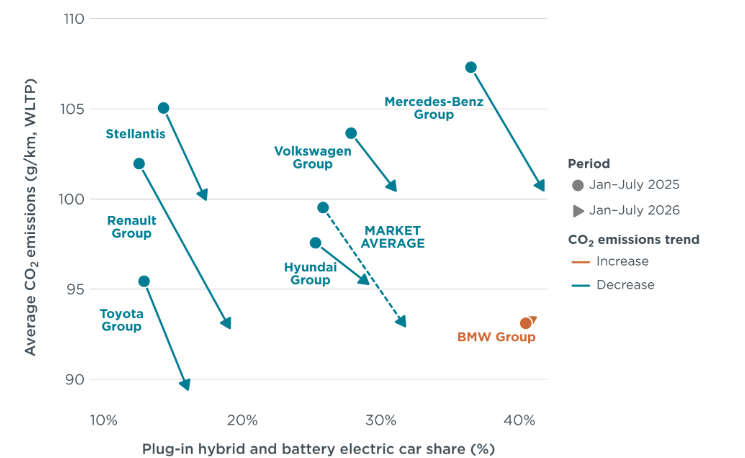
Looking at the relationship between electric car shares and average CO2 emissions in January–July 2026, the Mercedes-Benz Group stood out among the top manufacturers in Europe with some of the highest average emissions despite also having the highest combined share of PHEVs and BEVs. This was largely driven by the high-average CO2 emissions of the Group’s non-electrified powertrains, which stood at about 159 g CO2/ km in January–July 2026, the highest level among Europe’s largest carmaker groups.
By contrast, the Toyota Group, which has a focus on hybrid powertrains, recorded average CO2 emissions below its 2026 target in January–July 2026 despite maintaining the lowest electric vehicle share. Among Europe’s top manufacturers, the BMW Group was the only manufacturing group to see an increase in emissions in 2026 compared with the previous year. This reversal was partly due to a change in recorded PHEV emissions to more realistic levels resulting from the European Commission’s correction of the electric driving share assumed for type approval at the beginning of the year. However, it also mirrors a trend observed in previous CO2 target cycles: without interim annual targets, manufacturers often scale back CO2 reduction efforts once meeting their defined emissions target instead of using the momentum to reach the next target on a continuous reduction pathway. These delayed efforts have historically resulted in manufacturers claiming that the defined targets cannot be met and calling for last-minute policy action to
weaken the targets (see Figure 6). (5)
5 Sonsoles Díaz et al., CO2 Emissions from New Passenger Cars in Europe: Car Manufacturers’ Performance in 2024 (International Council on Clean Transportation, 2025), https://theicct.org/publication/co2-emissionsfrom-new-passenger-cars-in-europe-car-manufacturers-performance-in-2024-dec25/.
Figure 6 Fleet-average CO2 emissions compared with electric vehicle share by manufacturer group, January-July 2026 versus January-July 2025
Beyond the European countries included in this analysis, BEV market shares have grown substantially across a number of global markets in recent years.(6) Among the four largest passenger car markets by new sales (China, Europe, India, and the United States), China has recorded the strongest increases, surpassing Europe’s BEV share in 2021 and climbing to 35% in the first half of 2026 (see Figure 7). Although India remains a relatively small BEV market in terms of market share, its BEV share increased steadily from 2% in 2023 to 5% in January–June 2026. The country has set a nonbinding target for 30% of new vehicle sales to be electric by 2030. This target aligns with the country’s broader policy objectives to support BEV adoption and domestic production.(7) By contrast, BEV uptake in the United States has weakened since 2024, with the BEV share declining from 8% to 6% in January–June 2026. (8)
6 Ilma Fadhil and Chang Shen, Global Electric Vehicle Market Monitor for Light-Duty Vehicles, 2025 (International Council on Clean Transportation, 2026), https://theicct.org/publication/global-ev-marketmonitor- for-ldvs-2025/.
7 PIB Delhi, “Roads Reimagined: The Rise of India’s Electric Vehicles Ecosystem,” press release, August 5, 2026, https://www.pib.gov.in/PressReleaseDetail.aspx?PRID=2294688®=6&lang=1.
8 Chang Shen et al., The Global Automaker Rating 2025: Who is Leading the Transition to Electric Vehicles? (International Council on Clean Transportation, 2026), https://theicct.org/global-automaker-rating-2025/.
Figure 7 Share of battery electric passenger cars by country in selected global markets in 2023-2025 and January-June 2026
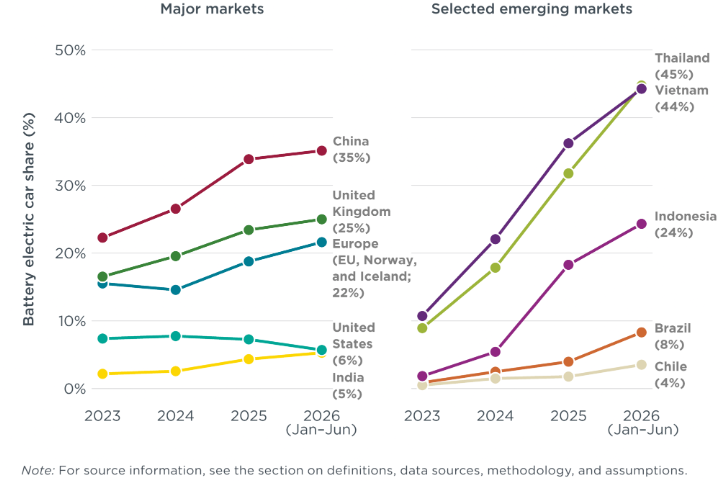
Looking at the United Kingdom (UK), which is outside the scope of the EU’s CO2 regulation, it experienced faster growth in BEV uptake than the combined market average for the EU, Norway, and Iceland. Following its departure from the EU in 2020, the UK introduced its own CO2 targets for new light-duty vehicles, together with a zero-emission vehicle mandate.(9) In the first half of 2026, one in four new car registrations in the UK was a BEV.
Among global markets with smaller car markets and more recent BEV uptake, Thailand and Vietnam stood out with substantial BEV market growth: in each country, BEV shares more than quadrupled from about 10% in 2023 to about 45% in the first half of 2026. Indonesia, meanwhile, caught up with Europe’s BEV market share: BEVs accounted for 24% of new car registrations in January–June 2026, up from 5% in 2024. Looking at South America, Brazil’s battery electric car share reached 8% in January– June 2026, double the BEV share in 2025.(10)
The think tanks Agora Verkehrswende (Germany), alinnea (Spain), ECCO Climate (Italy), the International Council on Clean Transportation (ICCT), the Mobility in Transition Institute (IDDRI-IMT, France), and the Polish Association for New Mobility (PSNM, Poland) publish monthly data on the average specific emissions of newly registered vehicle fleets in the European Economic Area, both overall and by country.
These data make it possible to track manufacturers’ compliance gap with respect to the CO₂ reduction targets (Regulation 2019/631) set for the 2025–2027 period, as well as the reduction of CO₂ emissions from new vehicles through 2035.
alinnea provides the report data with a particular focus on Spain, the fourth-largest automotive market in Europe.